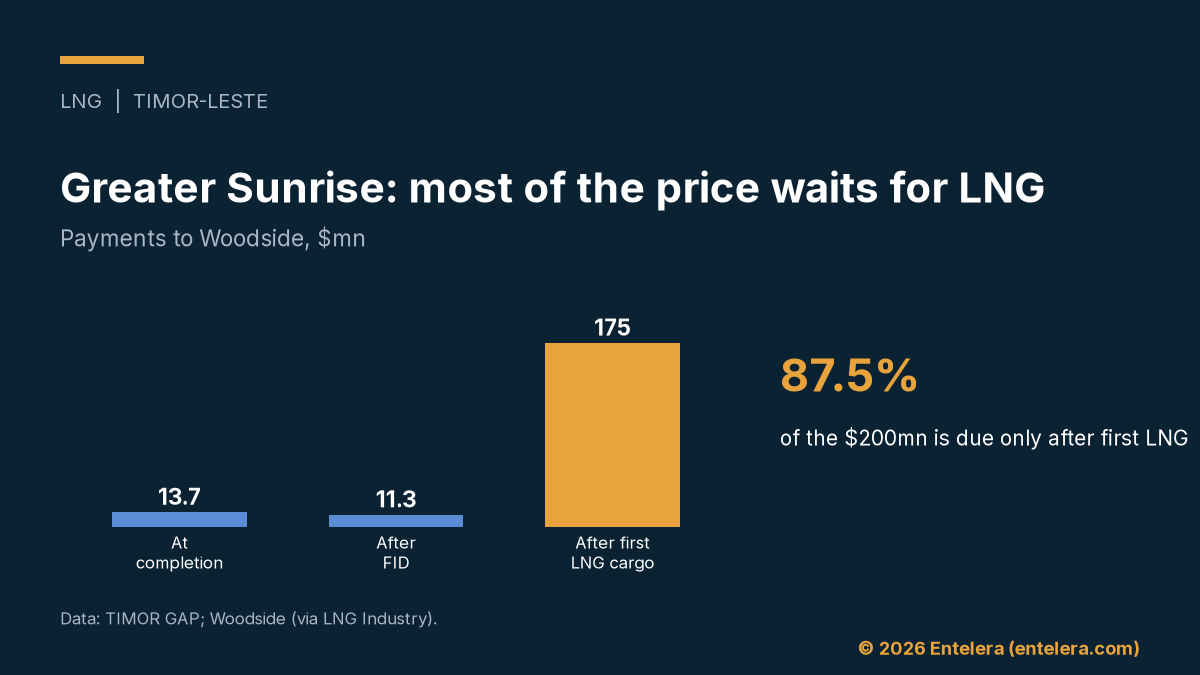
Greater Sunrise is about to have a single owner. On 27 October, Woodside agreed to sell its entire stake in the Timor Sea gas project to TIMOR GAP, Timor-Leste’s national oil company, for up to $200mn. However, the headline price hides the real deal. Only $13.71mn is due when the sale closes.
This analysis looks at what the payment terms say about the project’s risk, and why that risk now sits almost entirely with Timor-Leste.
How the Greater Sunrise price is built
The $200mn comes in three parts. First, $13.71mn arrives at completion, which Woodside targets for the first half of 2027. Second, $11.29mn falls due within 30 days of a final investment decision (FID). Third, $175mn is payable within 365 days of the first LNG cargo.
In other words, 87.5% of the price depends on LNG actually flowing. Only 6.9% is certain, on our estimate. Moreover, the first cargo is a long way off. In September, Timor-Leste’s petroleum minister pushed first production back to 2034-2035, with FID hoped for by 2029, ABC News reported.
What the deal says Greater Sunrise is worth
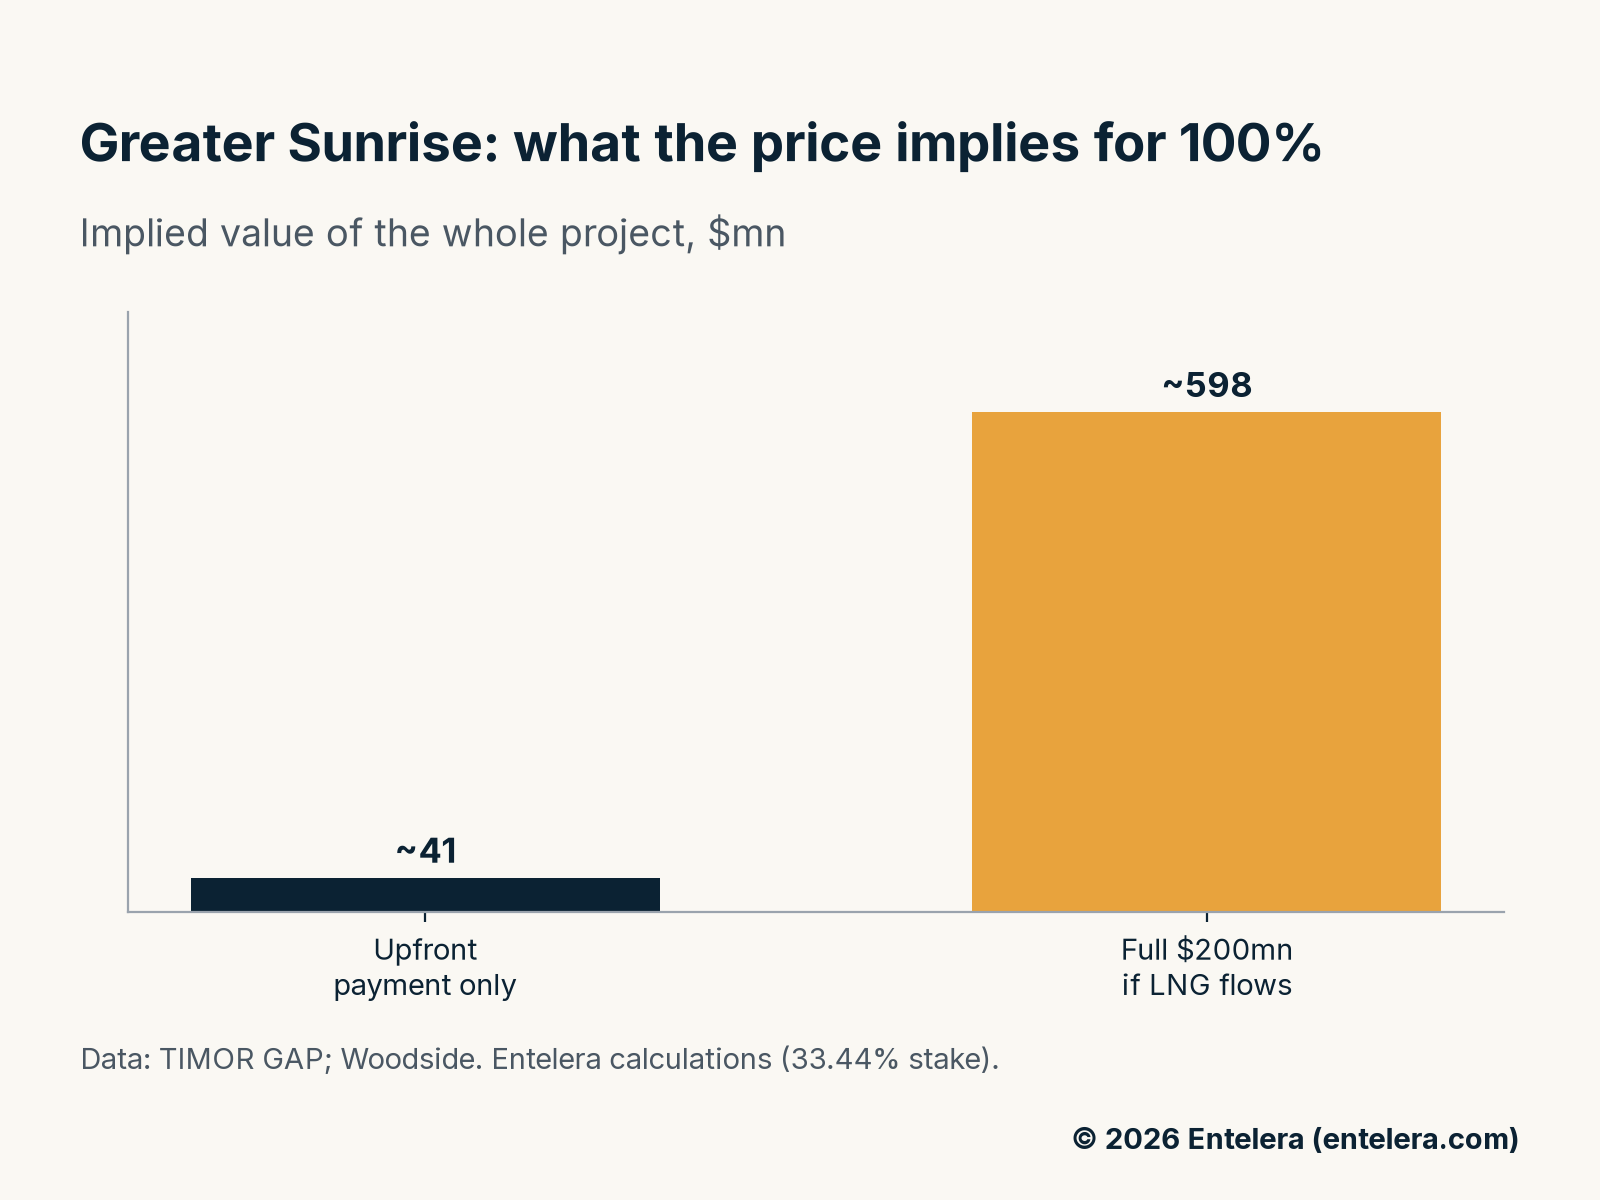
Woodside held 33.44% of the joint venture. On a simple pro-rata basis, the upfront payment values the whole project at about $41mn today. By contrast, the full $200mn implies about $598mn, on our estimate. That is small for 5.1 trillion cubic feet (~144bcm) of gas and 226mmbbl of condensate.
Indeed, the gap reflects old doubts about cost, not about the gas. For years, the partners disagreed over where to process it. Timor-Leste wants a pipeline to Natarbora on its south coast and a plant of about 5mtpa. However, analysts and industry sources still doubt that the onshore plan can pay its way, ABC News reported.
Why Woodside sold and TIMOR GAP bought
For Woodside, then, the logic is capital discipline. Chief executive Liz Westcott said the sale simplifies the portfolio and frees money for better returns. In effect, it swaps a stalled project for a free option on success. Similarly, other majors are selling what they do not control; see our analysis of TotalEnergies’ Nigeria exit.
For Timor-Leste, the stakes are national. Its Bayu-Undan field stopped producing last year. As a result, the state relies on a Petroleum Fund of about $26bn, which the IMF warned could run dry by 2038. TIMOR GAP already holds 56.56% and is buying Osaka Gas’s 10%. Therefore, it will need new partners and lenders to fund the build.
What to watch next
- The new production sharing contract and fiscal terms, which leaders hope to sign early next year.
- Concept selection for the Timor LNG plant.
- A new partner, possibly from Asia, to share the cost.
For the news, read our report on the Greater Sunrise sale.
Sources
- TIMOR GAP, TIMOR GAP to Acquire Woodside Energy’s Interests in the Greater Sunrise Project, 27 October 2026: timorgap.com
- LNG Industry, Woodside agrees Greater Sunrise sale to TIMOR GAP, 27 October 2026: lngindustry.com
- TIMOR GAP, Greater Sunrise project page (resources and partners): timorgap.com
- ABC News, Timor-Leste president says country to sign Greater Sunrise gas agreements within months, 18 October 2026: abc.net.au
- Upstream (via La’o Hamutuk), The wait is over: Sunrise gas will flow to Timor-Leste, November 2025: laohamutuk.org