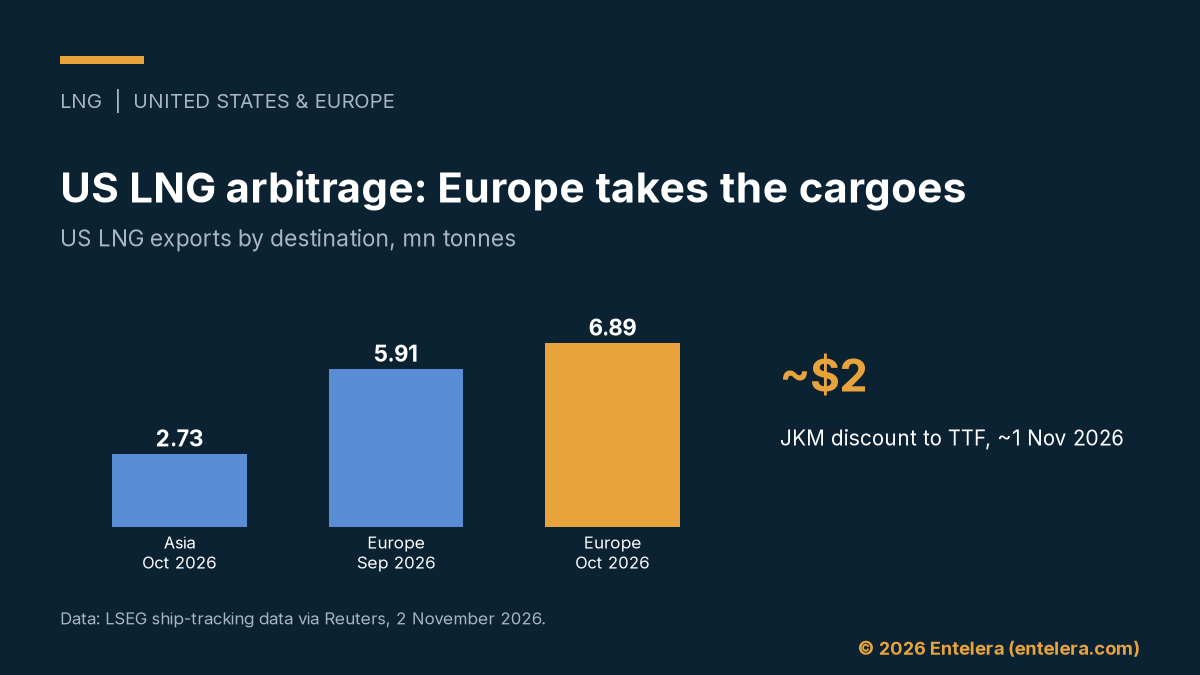
The US LNG arbitrage has swung firmly towards Europe. US exports reached their second-highest monthly level on record in October 2026, Reuters reported, citing LSEG ship-tracking data. Europe took 6.89mn tonnes, up nearly 1mn tonnes from 5.91mn tonnes in September 2026. Meanwhile, Asia took 2.73mn tonnes, down from 2.84mn tonnes.
This analysis looks at the spread behind that shift, and why it may hold into early 2027.
The Asian premium has gone
Normally, Asia pays more. Between March and July 2026, Asian spot LNG traded at a $2/MMBtu premium to Europe’s TTF hub, the IEA said. However, that gap shrank to ~$1/MMBtu in August to October 2026. By October 2026, TTF and JKM both averaged ~$28/MMBtu, according to Reuters.
Since then, the spread has flipped. Around 1 November 2026, TTF was near $34/MMBtu and JKM near $32/MMBtu, Reuters reported. On our reading, Asia now trades ~$2/MMBtu below Europe. Consequently, a flexible US cargo has no reason to take the longer voyage east.
How wide the US LNG arbitrage is
The US LNG arbitrage starts with a huge margin over US gas. December 2026 Henry Hub futures settled at $2.895/MMBtu on 3 November 2026, Dow Jones data show. Assuming a typical US contract price of 115% of Henry Hub plus a ~$2.50/MMBtu fee, a cargo costs ~$5.83/MMBtu at the terminal. So, against TTF near $34, the gross margin before shipping is more than $25/MMBtu, on our estimate.
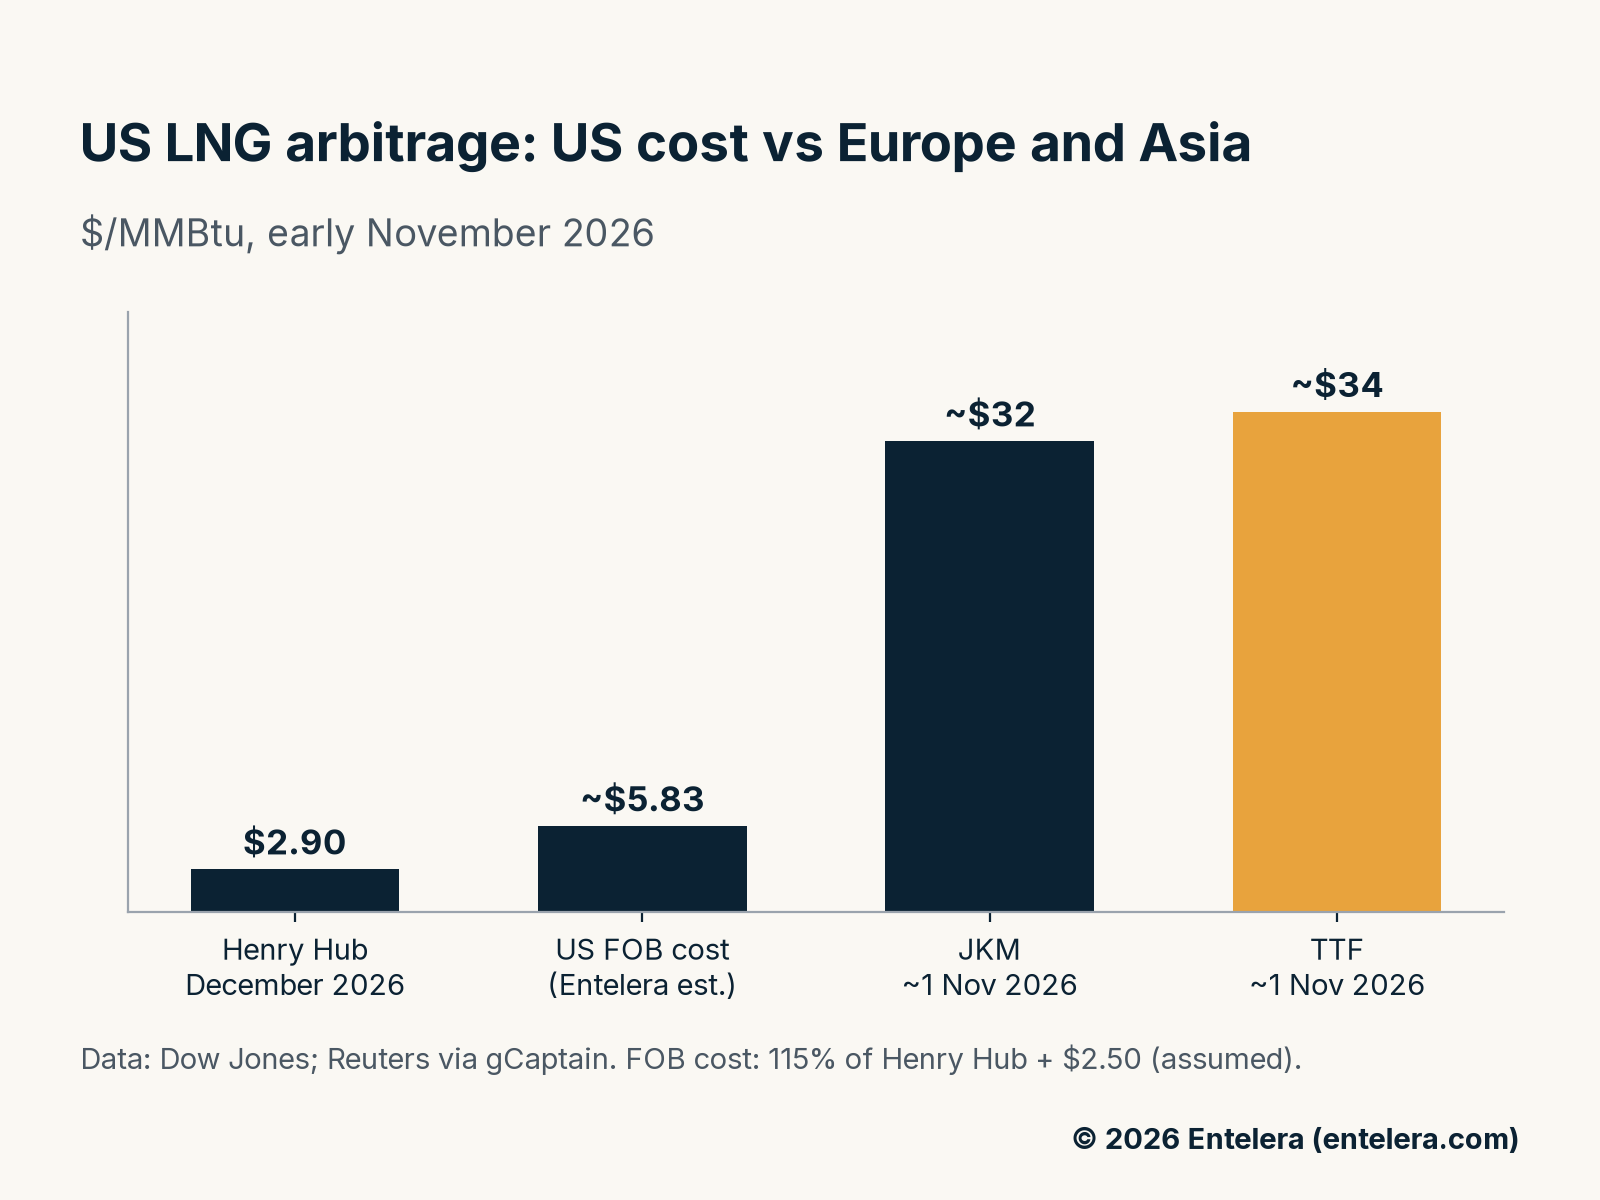
The question, therefore, is not whether to ship, but where. With Europe paying more and the voyage shorter, the US LNG arbitrage to Europe wins on both price and freight. In addition, Golden Pass LNG, owned by QatarEnergy and ExxonMobil, doubled its exports to four cargoes in October 2026.
Why Europe keeps bidding
Storage drives the bid. EU storage entered the 2026-27 heating season at its lowest level since 2013, the IEA said. In a cold winter with Hormuz still disrupted, its simulations show EU stocks below 10% of capacity by the end of March 2027. Also, withdrawal rates fall once sites drop below 30% full.
Supply is short, too. LNG loadings from Qatar and the UAE fell by over 60 bcm year on year in March to October 2026. Thus the IEA expects global LNG supply to fall by a record 3% in 2026. As a result, Europe must keep buying spot cargoes this winter and then refill hard in summer 2027. In our view, that argues for a flatter-than-usual TTF curve between winter 2026-27 and summer 2027. For the Qatari side, read QatarEnergy US LNG Deals: Why the Biggest Exporter Is Buying 7 mtpa as a Hormuz Hedge.
What could send US LNG arbitrage cargoes back to Asia
First, cold weather in North Asia would rebuild the JKM premium. Second, more volumes now move under contract. Plaquemines LNG Phase 1 started commercial operations on 31 October 2026. Its buyers include Sinopec and CNOOC Gas & Power as well as Shell, Orlen and EDF. Third, ~0.59mn tonnes left US terminals in October 2026 without a final destination, so those cargoes can still turn east if JKM rallies.
Oil indexation matters for Asia as well. Oil-indexed LNG reached ~$12-14/MMBtu in Q3 2026, and oil prices feed into contracts with a five to six month lag, the IEA said. Thus a lower Brent now would ease Asian contract prices only from ~Q2 2027.
What to watch next
- The TTF-JKM spread, which decides where flexible US cargoes go.
- Weekly EU storage data, against the IEA’s cold-winter path to below 10% by the end of March 2027.
- November 2026 US export data, as Plaquemines and Golden Pass ramp up.
Sources
- Reuters via Yahoo Finance, US LNG exports hit second-highest monthly level on record as Europe demand surges, 2 November 2026: uk.finance.yahoo.com
- Reuters via gCaptain, Venture Global begins supplying Plaquemines customers under long-term LNG contracts, 1 November 2026: gcaptain.com
- IEA, Global Gas Security Review 2026: Executive summary, 3 November 2026: iea.org
- Dow Jones via Morningstar, Front month Nymex natural gas rose 1.37% to settle at $2.8950, 3 November 2026: morningstar.com