Kirkuk Crude Exports: What Iraq’s Restart Means for Mediterranean Sour Spreads
Kirkuk crude exports restart via Ceyhan at 120,000 b/d, aiming for 500,000 b/d. What more Iraqi sour in the Mediterranean means for spreads and freight.
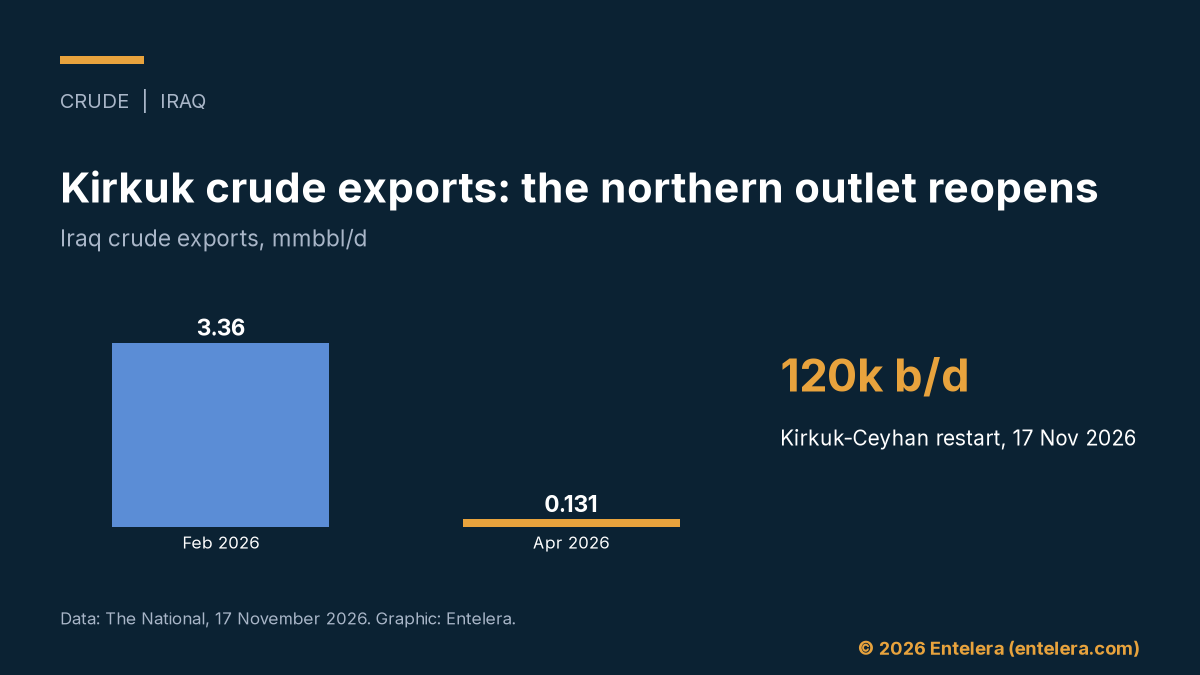
Kirkuk crude exports are back on the federal pipeline to Türkiye. Iraq restarted the 960 km Kirkuk-Ceyhan line on 17 November 2026 at 120,000 b/d, after 12 years out of service, as our news story on the Kirkuk-Ceyhan restart reported. The oil minister wants 500,000 b/d, with no date. For traders, the question is simple: where does more Iraqi sour go, and at what price?
Why Kirkuk crude exports matter for Iraq now
Iraq needs a route that avoids the Strait of Hormuz. Its exports fell from 3.36 mmbbl/d in February 2026 to 131,000 b/d in April 2026, The National reported. Moreover, more than 90% of the budget comes from oil export dollars. So every barrel of Kirkuk crude exports through the north counts.
The minister also said the northern outlet lets Iraq sell crude “without price discounts”. In other words, Baghdad sees Ceyhan as a way to price closer to Dated Brent than war-hit Gulf loadings allow.
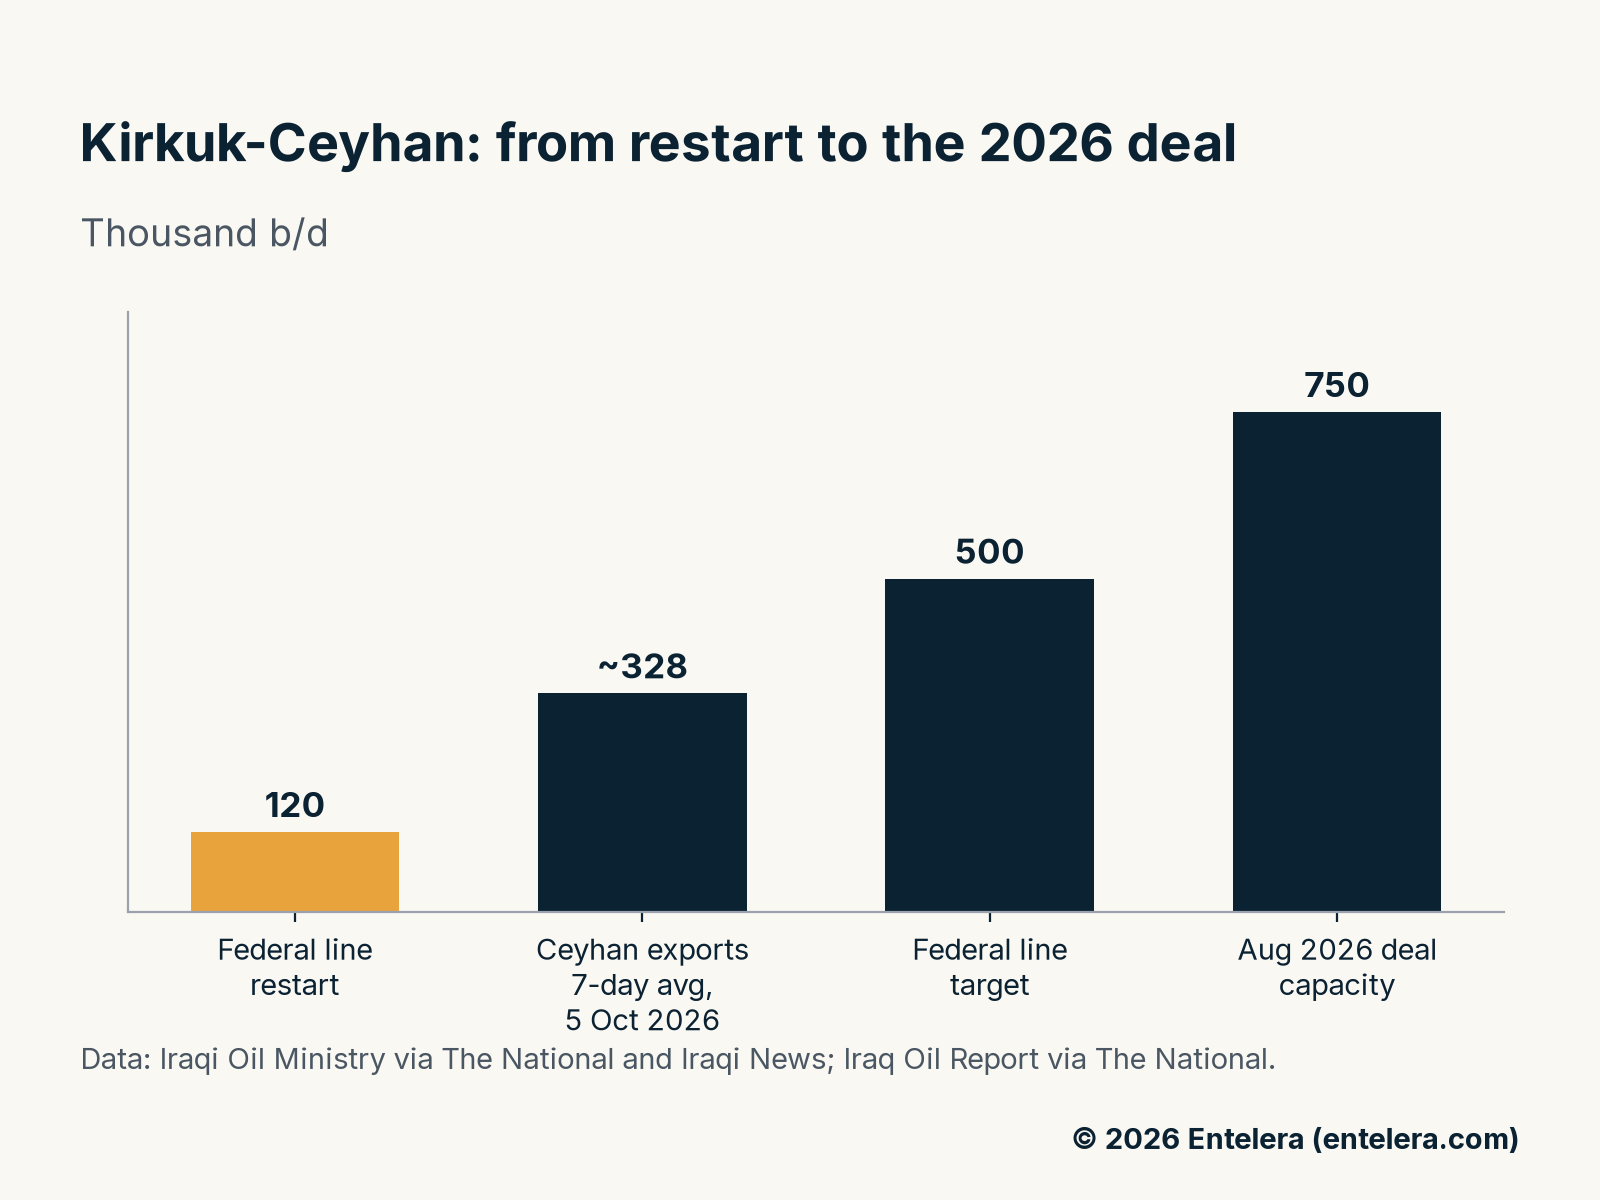
The headline 120,000 b/d is only part of the picture. Kurdish and Kirkuk crude already reaches Ceyhan through the Iraq-Türkiye pipeline, which reopened on 27 September 2025. Ceyhan exports averaged ~328,000 b/d in the seven days to 5 October 2026, Iraq Oil Report data cited by The National and Talay Insight showed. An unconfirmed oil company source quoted by Kurdistan 24 put flows nearer 500,000 b/d in early November 2026, including Basra crude trucked north.
However, nobody has said how much of the federal line’s 120,000 b/d is new oil. Some may simply move from the Kurdish line. Meanwhile, the August 2026 deal with Türkiye sets 750,000 b/d of capacity. On that basis, the pipe is not yet the limit; Iraq’s spare barrels are.
What more Iraqi sour means for Mediterranean spreads
Kirkuk crude exports consist of a medium sour grade of 34.2° API and 2.24% sulphur. That matters because it competes head-on with other sours in Europe, such as Norway’s Johan Sverdrup. When Kirkuk first returned in 2025, S&P Global noted weak bids and steep discounts to Dated Brent, while bearishness spread to CPC Blend.
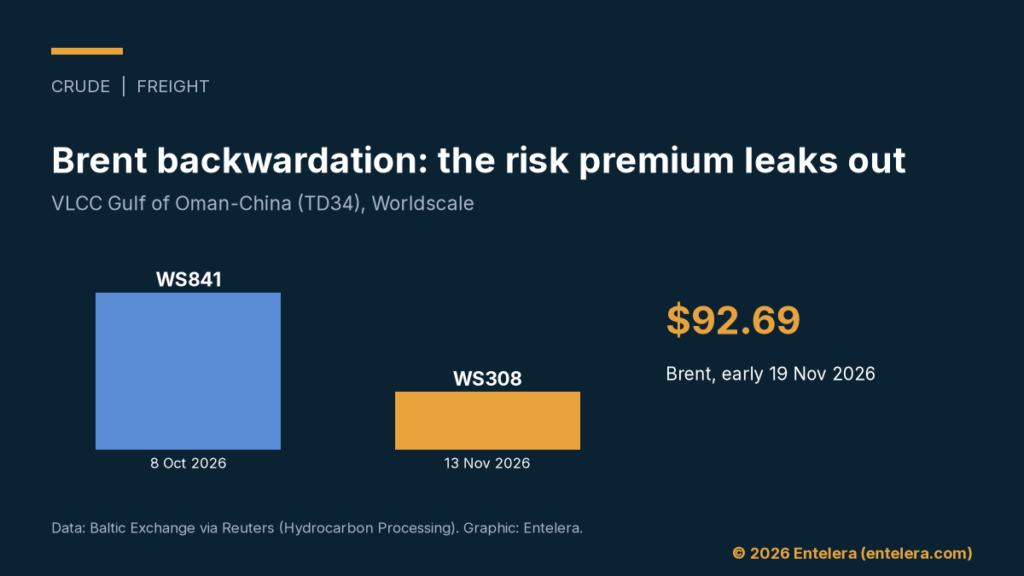
Today the setting is different. Brent settled at $93.14 a barrel on 17 November 2026, as our oil price story reported, and Gulf sour supply is still disrupted. As a result, a sour-short Mediterranean can absorb more Kirkuk than in 2025. Yet if Hormuz flows normalise, the extra barrels at Ceyhan would weigh on sour differentials again.
What Kirkuk crude exports mean for traders and buyers
Traders: as Kirkuk crude exports grow, watch the grade’s discount to Dated Brent. A ramp-up towards 500,000 b/d should widen it, unless Gulf supply stays tight.
Portfolio players: the Ceyhan barrel is a short-haul, Hormuz-free sour. That optionality is worth a premium while war risk persists.
Refiners: Mediterranean and Turkish plants gain a pipeline-fed sour option, which cuts freight and insurance exposure.
Freight: 750,000 b/d needs about 37 loadings a month, Talay Insight estimates, which would support Eastern Mediterranean tanker demand.
What to watch next
SOMO’s monthly Ceyhan sales and whether federal flows rise above 120,000 b/d before the end of December 2026.
Kirkuk and Johan Sverdrup differentials against Dated Brent through Q1 2027.
Basrah loadings in the Gulf, because a Hormuz recovery would reduce the value of the northern route.
The Basra-Haditha pipeline, a planned 2.5 mmbbl/d link that would change Iraq’s export map.
Sources
The National, Iraq resumes pumping crude oil for export through pipeline to Turkey, 17 November 2026: thenationalnews.com
Iraqi News, Iraq resumes oil flows via rehabilitated Kirkuk–Ceyhan pipeline, 17 November 2026: iraqinews.com
Anadolu Agency, Iraq approves rehabilitation of oil pipeline to Türkiye as flows resume after 12 years, November 2026: aa.com.tr
General Index, Crude oil Kirkuk FOB Ceyhan vs Dated Brent factsheet: g-x.co
S&P Global, Kirkuk crude resurgence: navigating new trade dynamics, October 2025: spglobal.com
Talay Insight, As Hormuz reopens, Ceyhan’s bargaining window is closing, November 2026: talayinsight.com
Talay Insight, Kirkuk reopens, but Iraq’s spare barrels cap the overland route, November 2026: talayinsight.com
Free account
Sign up free to read the full analysis
Create a free Entelera account to read every analysis in full. It takes less than a minute; no payment details needed.
Entelera Research is the editorial team behind Entelera. We cover crude, LNG, power, renewables, policy and geopolitics, looking at energy the way companies have to: supply, demand, margins, policy and risk, with every number linked to its source and a close eye on India and its place in global markets.
Mexico fuel imports barely moved as Pemex runs fell ~210,000 b/d in September 2026, while crude exports jumped. What it means for USGC cracks and Maya.