Guyana crude exports are already reshaping the Atlantic Basin, and Longtail adds a new layer. ExxonMobil took a $12.5bn investment decision on the project on 12 November 2026, as our news story on the ExxonMobil Longtail FID reported. Longtail is a gas project. However, for oil traders the key number is 250,000 b/d of condensate from 2030.
This analysis looks at where Guyana’s barrels go today. It then asks what more light sweet supply means for differentials, flows and buyers.
Guyana crude exports today: Europe takes the barrels
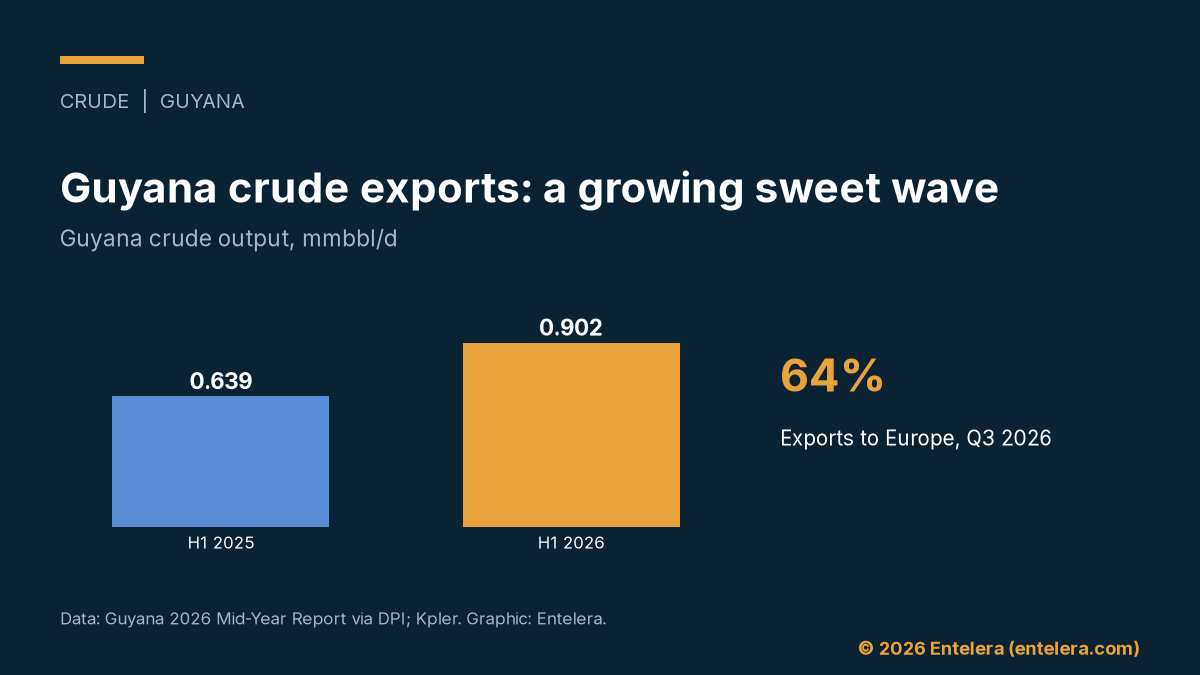
Guyana produced about 0.902 mmbbl/d in H1 2026, up from 0.639 mmbbl/d a year earlier, the government’s Mid-Year Report said. Output dipped in August 2026. Then it recovered to ~0.906 mmbbl/d in September 2026, OilNOW reported from government data.
Moreover, the destination mix has shifted hard. Europe took 64% of Guyanese exports in Q3 2026, up from 52% in Q4 2025, Kpler said. By contrast, Guyana sent no cargoes to East Asia in Q3 2026. High long-haul freight and war-risk premiums closed that arbitrage.
Why sweet differentials are under pressure
The problem is quality, not volume. Guyana’s grades are light to medium sweet, and Brazil’s pre-salt barrels are medium sweet. Yet the market is short of medium sour crude, as OPEC+ producers pump below quota. As a result, sweet barrels are piling up in North-West Europe, Kpler said.
That has two effects. First, regional sweet differentials weaken. Second, the transatlantic arbitrage for WTI Midland narrows, so more US crude heads to Asian tenders. Meanwhile, the flat price is volatile. Brent settled at $95.82 a barrel on 12 November 2026, yet it is still down 18.55% in November.
WTI settled at $88.74 on the same day. On our calculation, that leaves the front-month WTI-Brent spread at ~$7.08, although the contracts are for different months.
Longtail and the next wave of Guyana crude exports
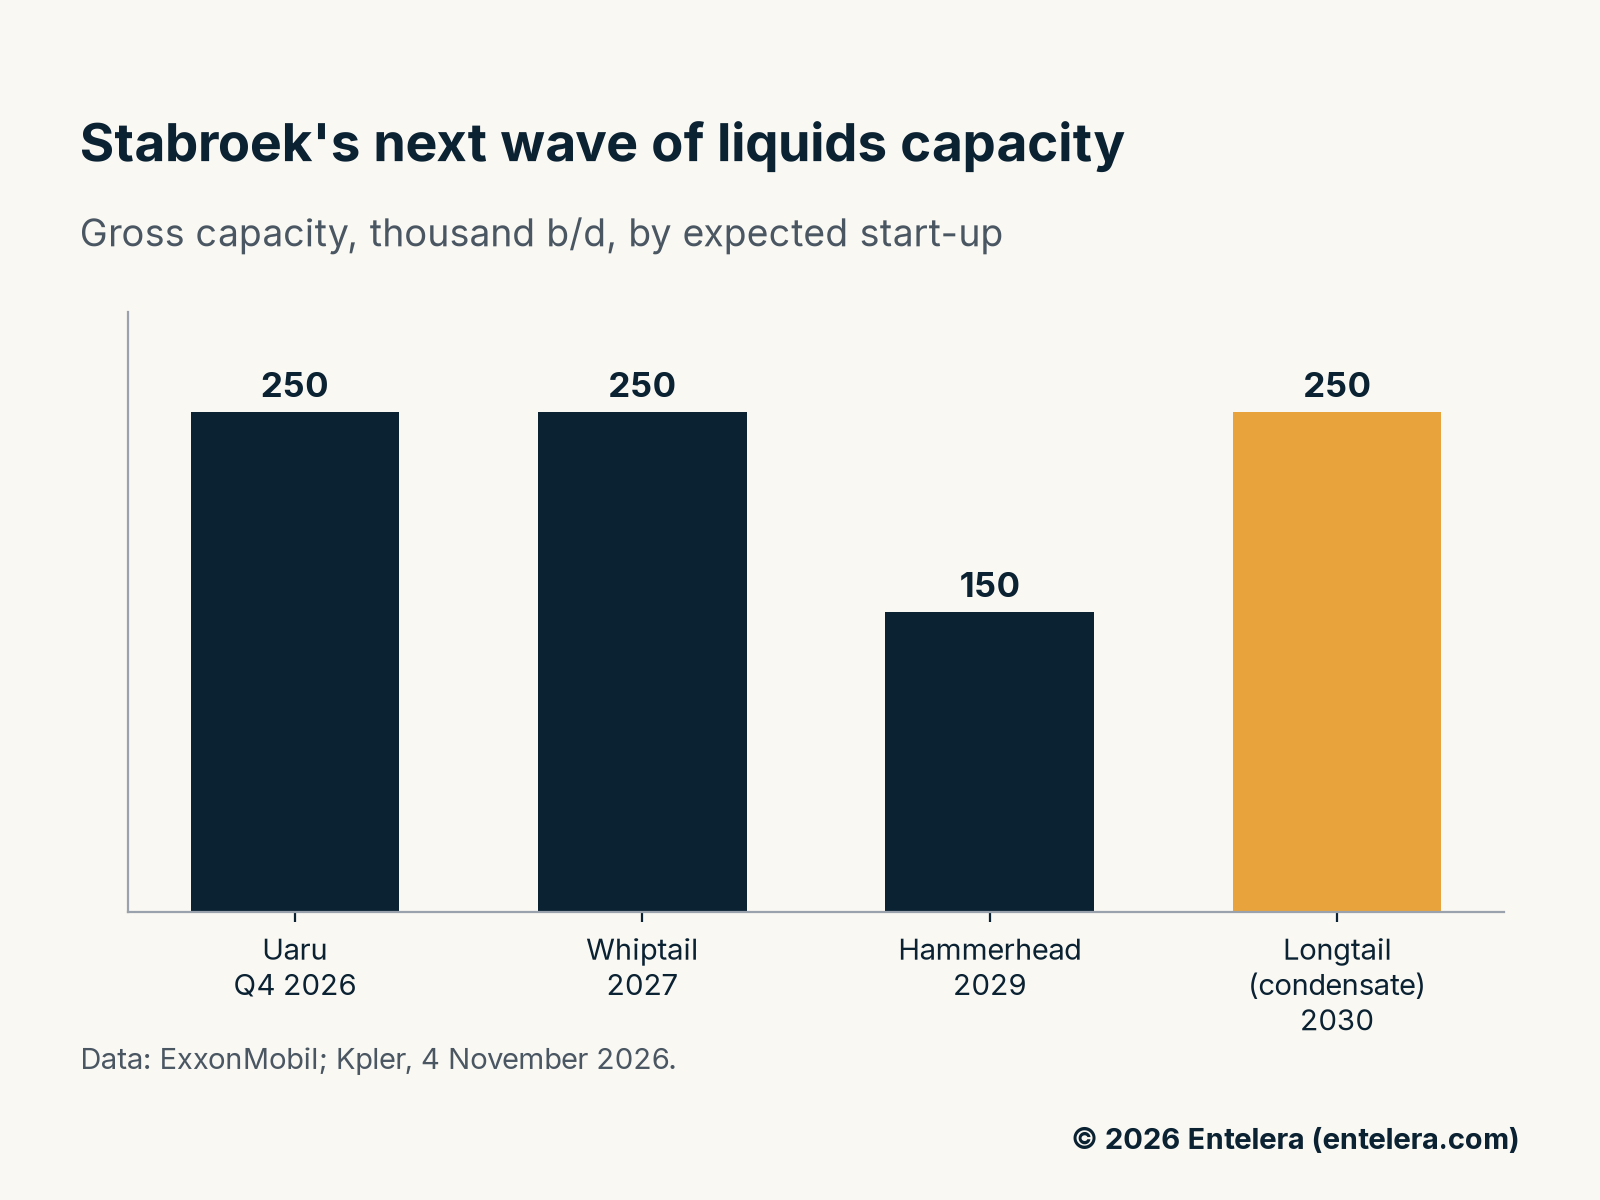
In fact, Longtail is the last link in a long chain. Uaru, with 250,000 b/d of gross capacity, should load first cargoes in mid-December 2026, according to market talk cited by Kpler. Whiptail adds 250,000 b/d in 2027 and Hammerhead 150,000 b/d in 2029. Then Longtail brings 250,000 b/d of condensate in 2030.
On our sums, that is 900,000 b/d of new gross liquids capacity in about four years. Guyana itself targets 1.7 mmbbl/d by 2030, The National reported. Condensate is also lighter than Guyana’s crude, so it competes with other naphtha-rich barrels such as US condensate.
Gas is a slower story. The Longtail vessel can handle about 1.2bn cubic feet a day, or ~12.4 bcm a year on our maths. However, 18 of its 45 wells will inject gas back into the reservoirs. So, in our view, condensate drives the early value.
What Guyana crude exports mean for traders
For refiners in Europe, more Guyana crude exports mean cheaper sweet feedstock and more choice. For sour-short Asian buyers, they help less, unless freight falls and the East Asia arbitrage reopens. Also, when Gulf barrels return, they meet an Atlantic market where sweet grades already hold share.
What to watch next
- First Uaru cargoes in mid-December 2026, and whether national output passes 1 mmbbl/d.
- Guyana loadings to East Asia, a direct read on long-haul freight and the sweet arbitrage.
- North-West Europe sweet differentials against Brent as Brazilian and Guyanese supply grows.
- The WTI-Brent spread, which sets how hard US crude must push into Asia.
Sources
- ExxonMobil (Business Wire), ExxonMobil Advances Next Phase of Guyana Development with Longtail, 12 November 2026: businesswire.com
- Kpler, Brazil and Guyana show Q4 crude supply promise, 4 November 2026: kpler.com
- OilNOW, September Guyana oil output recovers from slump to 906,000 b/d, October 2026: oilnow.gy
- Department of Public Information Guyana, Guyana’s oil exports surpass US$15B in first half of 2026: dpi.gov.gy
- The National, Guyana: the tiny country with big ambitions fast emerging as a global oil producer, 7 October 2026: thenationalnews.com
- Dow Jones via Morningstar, Front month ICE Brent crude rose 3.30% to settle at $95.82, 12 November 2026: morningstar.com
- CNBC, Oil prices rise after Trump says no Iran deal needed, 12 November 2026: cnbc.com